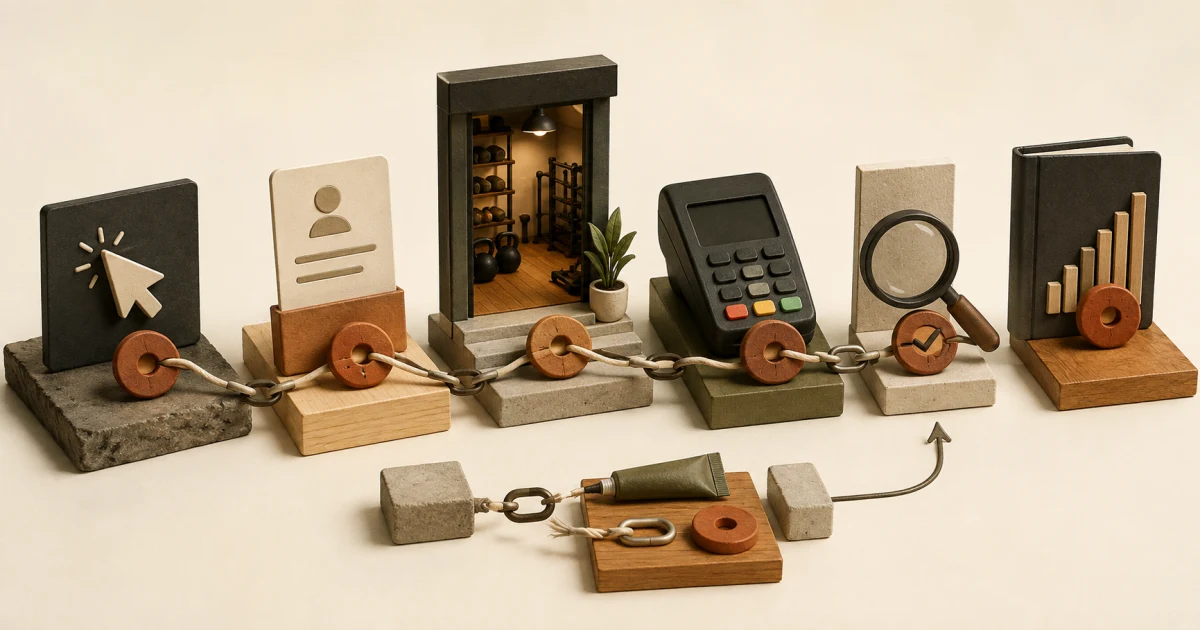
An advertising dashboard can show a low cost per lead while the gym loses money on every member acquired. The lead is only the first counted event. Sales time, trial delivery, discounts, failed payments, and early cancellations arrive later.
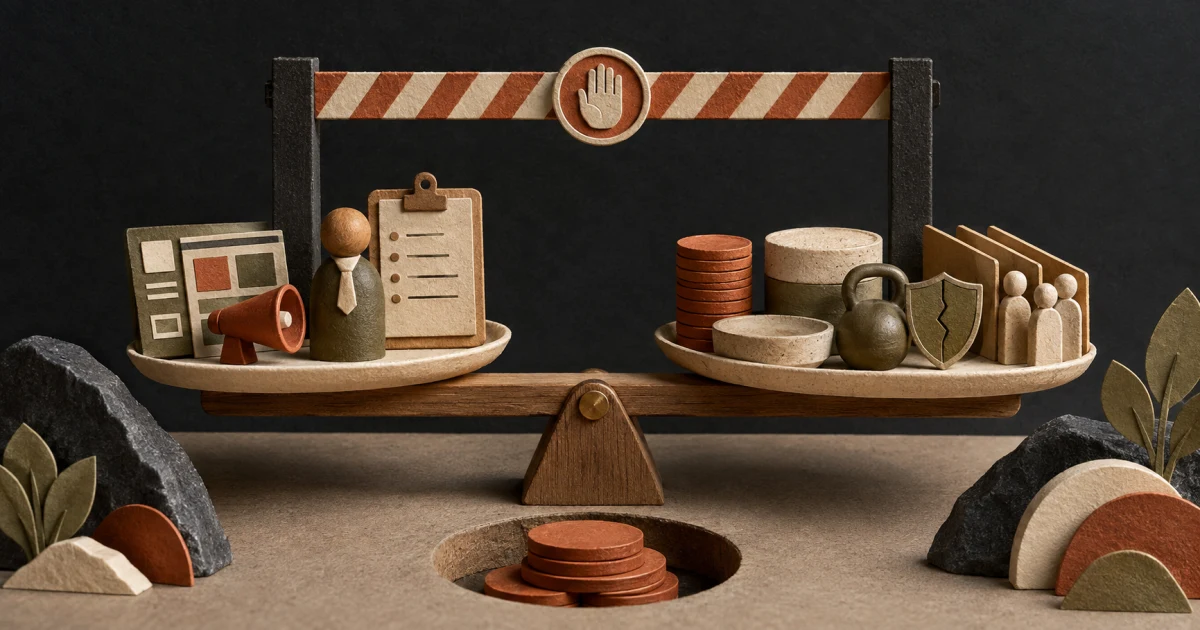
A gym can afford to acquire a member only up to the conservative collected contribution available inside its chosen payback window, after preserving the operating contribution and risk reserve the business needs. Calculate a fully loaded new-member CAC first. Then subtract non-media acquisition costs to find the maximum media cost per paid member.
This is the Cluster D pillar. It connects campaign decisions to real economics rather than borrowed benchmarks.
Keep six acquisition numbers separate
Use one definition for each stage:
| Metric | Calculation | What it answers |
|---|---|---|
| Cost per lead | Media spend divided by captured leads | What did a form or call cost? |
| Cost per contactable lead | Media spend divided by leads the team could reach | Were the contact details useful? |
| Cost per qualified lead | Media spend divided by leads meeting the stated fit rule | Did the channel find relevant prospects? |
| Cost per attended tour or trial | Media spend divided by people who actually attended | Did the funnel create a real visit? |
| Media cost per paid member | Media spend divided by new members meeting the payment rule | What did advertising alone cost per join? |
| Fully loaded new-member CAC | All attributable acquisition cost divided by paid members | What did the complete acquisition process cost? |
The platform may label a form submission “conversion” or “acquisition”. Your gym’s accounting definition still controls whether that person became a paying member.
Define a paid member before doing the maths
Write one rule that the sales and finance records can verify. For example:
A new paid member has signed the current agreement, paid the required first amount, cleared any payment validation, and is not an existing member changing plans.
Decide how you treat refunds, cooling-off periods, reversals, complimentary memberships, reactivations, and family plans. Do not change the rule between campaigns to make one channel look better.
Use the offline conversion guide to preserve the click-to-payment trail.
Calculate fully loaded new-member CAC
Add the costs caused by acquiring the cohort:
- advertising spend;
- agency or campaign-management cost allocated to the period;
- creative production allocated under one documented method;
- landing-page or lead-tool cost attributable to acquisition;
- sales calls, messages, appointments, and tour labour;
- trial delivery, welcome items, commissions, and joining incentives;
- discount value inside the chosen payback window;
- payment, refund, and failed-collection costs caused by the cohort.
Then calculate:
Fully loaded new-member CAC = total attributable acquisition cost ÷ verified new paid members
Keep fixed business overhead separate unless the decision genuinely changes it. The objective is not to allocate every rupee in the company. It is to stop material acquisition cost from disappearing outside the ad dashboard.
Build the economic ceiling from collected contribution
Choose a payback window the gym can finance. Do not begin with a universal three-month, six-month, or lifetime rule.
For a conservative acquired-member cohort:
Collected gross contribution = cash collected in the window - variable service and collection costs
Variable costs can include trainer delivery, class capacity, consumables, payment fees, member-specific onboarding, and expected refunds. Use collected cash, not the headline contract value, unless collection is genuinely certain under the model.
Then set:
Maximum fully loaded CAC = conservative collected gross contribution - required operating contribution - risk reserve
Finally:
Maximum media cost per paid member = maximum fully loaded CAC - non-media acquisition cost per paid member
If this result is negative, paid acquisition does not have an economically safe media allowance under the current assumptions. Fix price, delivery cost, conversion, retention, collection, or the offer before increasing spend.
Copy this CAC ceiling worksheet
| Input per acquired member | Conservative value | Evidence and period |
|---|---|---|
| Cash expected to be collected in the payback window | ||
| Expected refunds and failed collections | ||
| Variable coaching or service delivery | ||
| Payment and member-specific operating cost | ||
| Collected gross contribution | ||
| Operating contribution the gym must preserve | ||
| Risk reserve for uncertainty | ||
| Maximum fully loaded CAC | ||
| Sales and follow-up labour | ||
| Trial, incentive, and commission cost | ||
| Allocated creative, tool, and agency cost | ||
| Maximum media cost per paid member |
Document who owns every input. Finance should verify collections and refunds. Operations should verify delivery capacity and cost. Sales should verify labour and paid-member status. Marketing should verify media and creative cost.
Work through a fictional example
This example is fictional and is not an industry benchmark.
Suppose a gym expects to collect ₹9,000 from a conservative new-member cohort during its chosen payback window. Expected variable delivery, payment, and refund cost is ₹2,200. Collected gross contribution is therefore ₹6,800.
The owner requires ₹3,300 of operating contribution and a ₹900 risk reserve:
- maximum fully loaded CAC = ₹6,800 - ₹3,300 - ₹900 = ₹2,600;
- sales labour, trial delivery, commissions, and allocated creative total ₹1,050 per paid member;
- maximum media cost per paid member = ₹2,600 - ₹1,050 = ₹1,550.
If 20% of qualified paid-campaign leads become verified paid members, the provisional media ceiling per qualified lead is ₹310. That does not make ₹310 a universal target. A lower join rate, poorer collection, or higher delivery cost lowers the ceiling.
Add uncertainty instead of hiding it
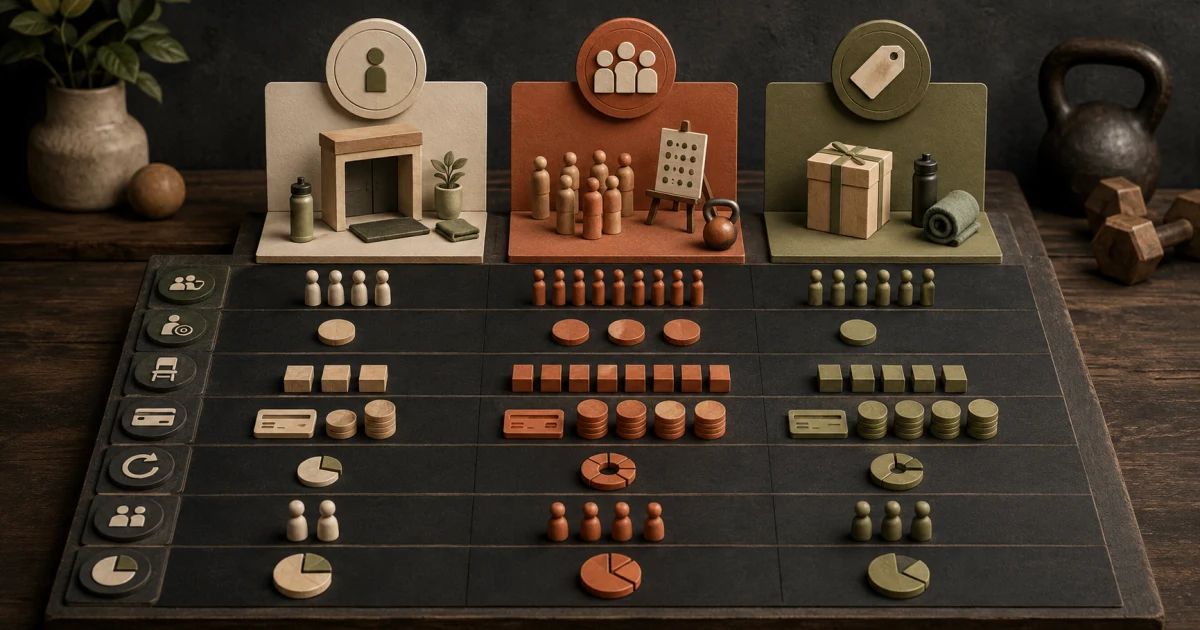
Build conservative, base, and strong cases for:
- collection inside the window;
- trial attendance and paid-join conversion;
- discount and refund cost;
- early cancellation;
- sales labour;
- service delivery at peak times;
- member retention beyond the payback window.
Approve spend from the conservative case until enough cohort evidence supports a change. Lifetime value can inform strategy, but distant revenue is uncertain and cannot automatically fund this month’s cash outflow.
Use the Cluster D operating map
| Decision | Gym Ledger guide |
|---|---|
| Choose an on-platform or website lead path | Meta form versus landing page |
| Compare a free trial, paid trial, challenge, discount, or no discount | Gym offer economics |
| Organise local high-intent search demand | Google Search Ads for gyms |
| Stop irrelevant search spend without blocking real demand | Negative keywords for gym ads |
| Test how far paid campaigns should reach | Gym ad radius and catchment test |
| Qualify without turning the first form into medical intake | Short gym enquiry forms |
| Set retargeting consent, audience, and creative limits | Gym retargeting controls |
| Learn which creative variable changed performance | Gym ad creative testing matrix |
| Reconcile ad clicks with collected memberships | Offline conversion tracking |
The pillar sets the economic boundary. The spokes help the team improve one part of the acquisition system without losing the paid-member definition.
Run a weekly acquisition ledger
| Cohort and source | Spend | Valid leads | Qualified | Attended | Paid members | Collected | Fully loaded CAC | Ceiling | Decision |
|---|---|---|---|---|---|---|---|---|---|
Do not scale a channel merely because its cost per lead is lower. Check whether differences in geography, offer, form, response speed, follow-up, capacity, or collection explain the result.
Set stop and review rules before spending
Pause or investigate when:
- tracking cannot distinguish a lead from a paid member;
- projected fully loaded CAC breaches the conservative ceiling;
- contactability or qualification deteriorates materially;
- the team cannot respond within the promised process;
- onboarding or coaching capacity is being damaged;
- refunds, complaints, or early cancellations rise;
- consent, claim, or audience use cannot be verified.
A test can be inconclusive. Do not manufacture certainty from three joins or one unusually strong week. Record the evidence, limitation, and next smallest test.
Frequently asked questions
How do you calculate customer acquisition cost for a gym?
Add attributable media, agency, creative, sales labour, trial, incentive, commission, tool, and related acquisition costs for a defined cohort, then divide by verified new paid members under one consistent rule. Keep this fully loaded CAC separate from platform cost per lead.
How much should a gym spend to acquire one member?
There is no universal amount. Start with conservative cash contribution expected inside a chosen payback window, subtract required operating contribution and a risk reserve, then subtract non-media acquisition costs to find the maximum media cost per paid member.
Should a gym use lifetime value to set its CAC target?
Lifetime value can inform a long-term decision, but gross lifetime revenue is not an acquisition budget. Use conservative collected contribution, retention evidence, cash timing, delivery cost, uncertainty, and the amount the business must preserve before setting the ceiling.